Equipment finance
Equipment and vehicle finance for your business.
Cars, utes, trucks, machinery and plant, financed with the asset as security and repayments that suit your cash flow.
Equipment finance in short
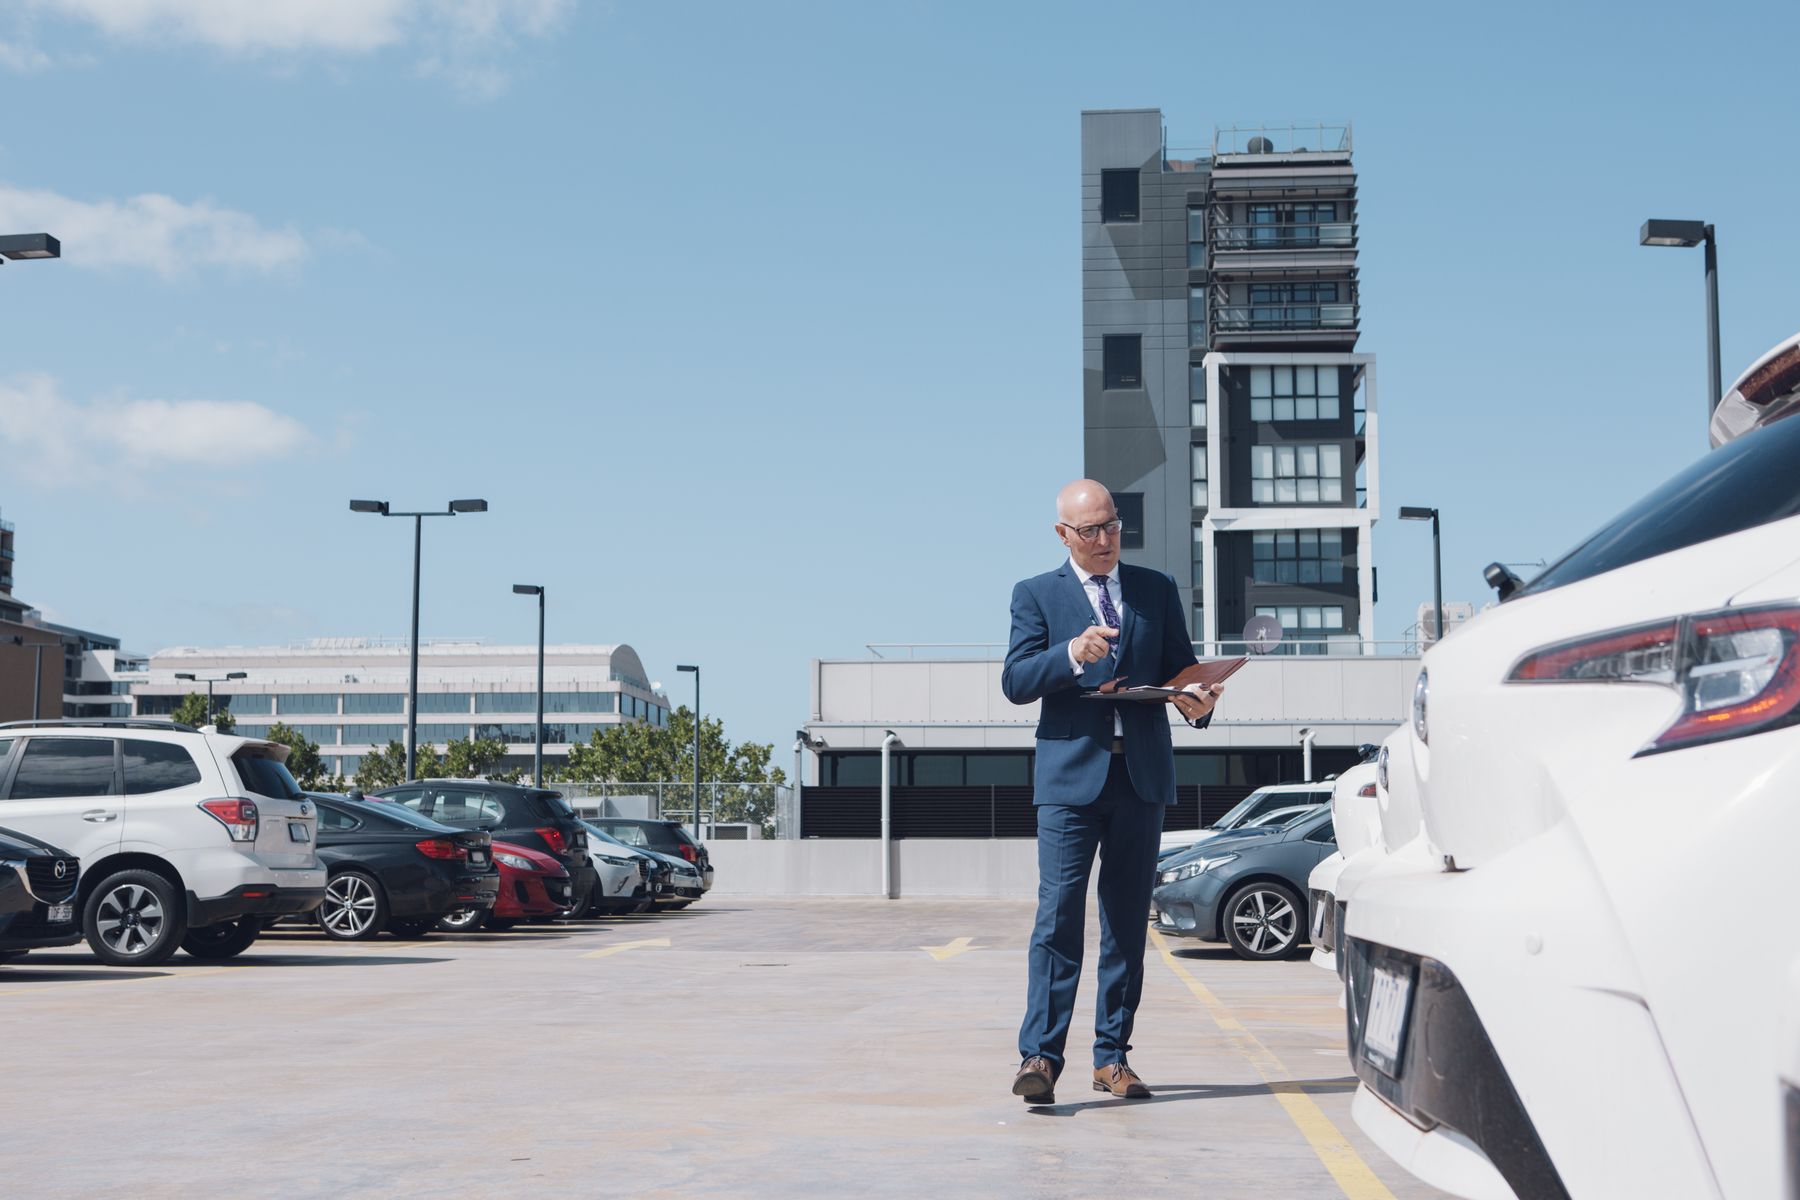
Equipment finance funds new or used vehicles, trucks, machinery and plant, usually secured by the asset itself. MKS Lending compares lenders and structures the term and residual to suit your cash flow, so your business keeps its working capital.
How equipment finance works
Buy the asset, use it as security.
Equipment finance is a loan for buying new or used equipment and vehicles, usually secured by the asset itself. That means you can often fund the purchase without using property as security.
You can adjust your repayments by choosing a residual, or balloon, payment at the end of the term, which you pay out or refinance. Repayments on assets used for business may be tax deductible; please confirm with your accountant.
What we finance
From utes to excavators.
Yellow goods
Earthmoving machinery such as bobcats, loaders and excavators, plus agricultural machinery like tractors, harvesters and sprayers.
Heavy trucks
Prime movers, trailers and accessories.
Machinery and plant
Generators, conveyors and plant fit-outs.
Motor vehicles
New or used cars and utes, including older models, from a dealer or private sale.
Benefits
Why businesses use equipment finance.
The asset is the security
No need to tie up property for most equipment purchases.
Flexible repayments
Choose a residual to manage monthly cash flow.
You own it
Ownership through the asset's useful life with a chattel mortgage.
Protect your cash flow
Keep working capital for running the business.

Business lending, handled by people who speak your language
Our team has arranged business, commercial and development finance since 1985, often working directly with your accountant and solicitor so the loan supports the bigger plan.
Client reviews
What our clients say.
Teo understands finance and made the loan process stress-free.
Teo did all the hard work with the bank and we concentrated on our business.