 Written by Gareth Sweeney
 Reviewed by Teo Torrelli, Director and Senior Mortgage Broker
 From time to time, a business needs a cash injection. With so many lenders offering a dizzying array of products, it can be difficult to know what to choose.
There are plenty of business loans available, but before diving in and applying, it’s important to understand your requirements first, so that a loan can be matched to your needs, and so that you can potentially avoid the problem in the future.
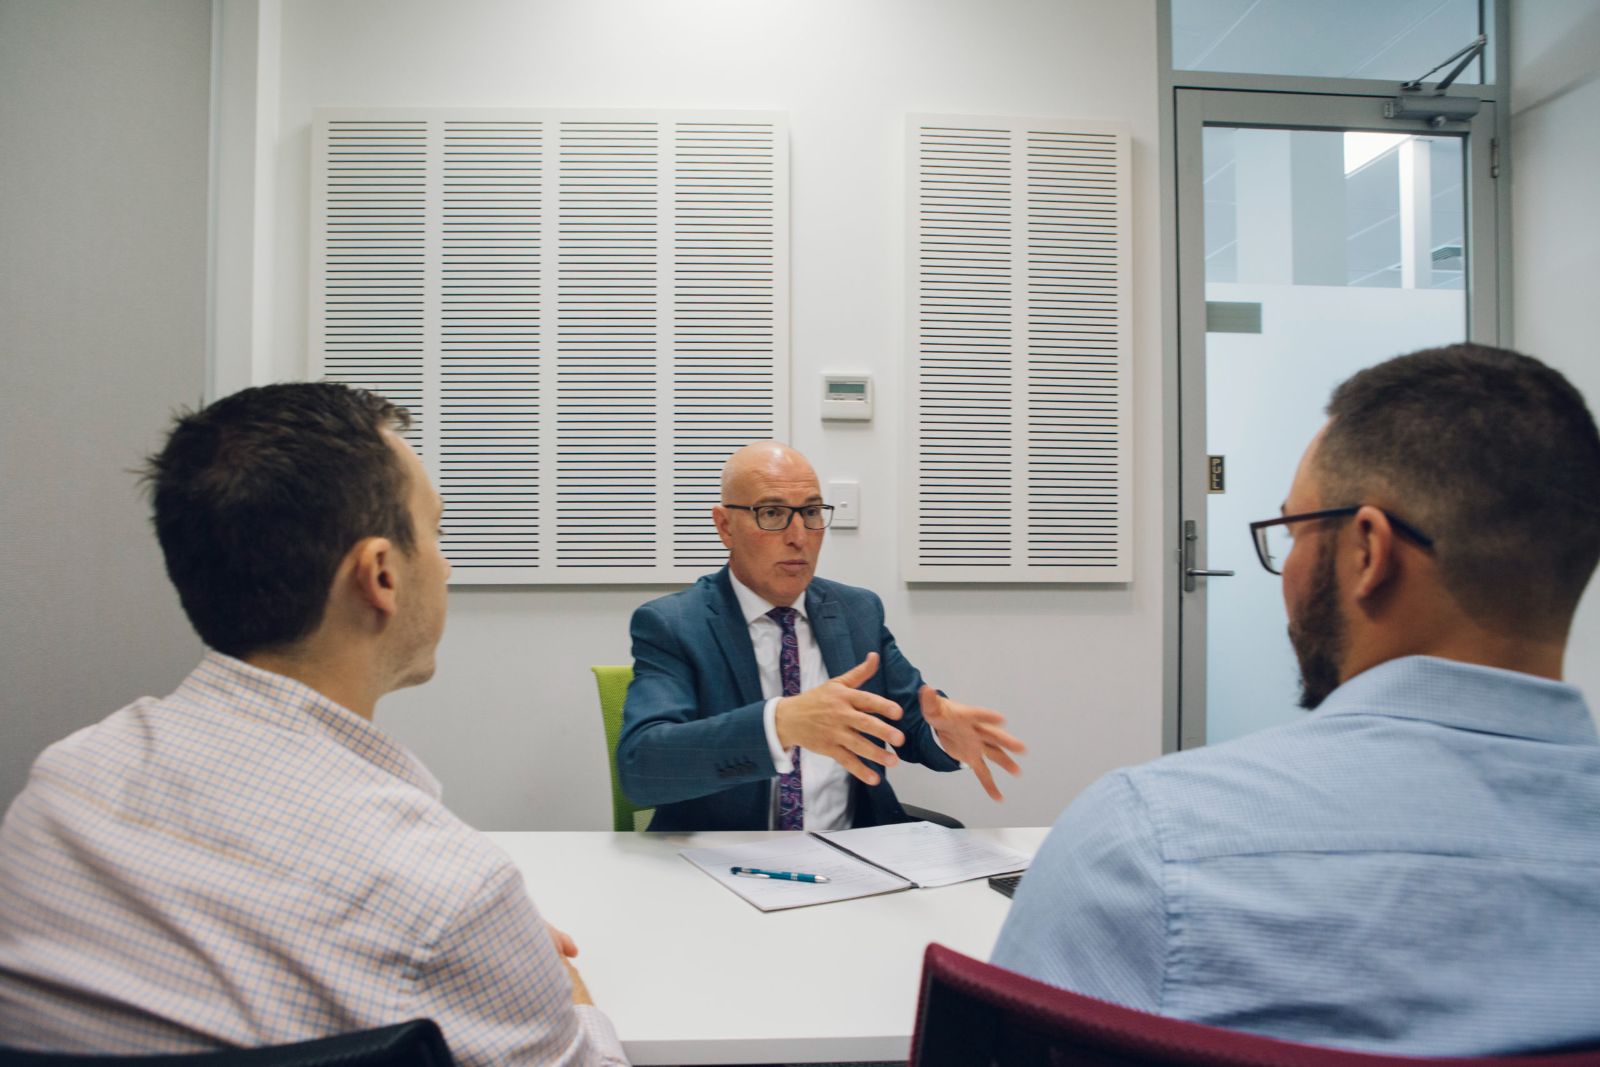
“Do your homework first, because if you don’t, you’re going to buy the wrong product,” says experienced Mortgage Broker Teo Torrelli, Director at MKS Lending Group. “There are hundreds of ways of getting the money, but you’ve got to match those with the purpose.”
The consequences of choosing the wrong finance product include paying too much for finance, or ending up with a loan that simply isn’t fit for the purpose – in this case it may make a problem worse, rather than solving it.
“It comes down to finding out what your real issue is,” says Teo. Work out how long it will take to repay the amount you need to borrow, whether the repayments will impact the business, what has caused the shortfall and whether you need to take any other action.
“A lot of people in need of short-term debt might not be invoicing properly or collecting their debts properly,” says Teo.
Finally, make sure you talk to someone experienced before talking to bank staff, who may not have specialist knowledge of small businesses, or a good understanding of your business and its needs. Teo suggests speaking to your accountant, financial planner or solicitor.
Contact MKS Lending Group, specialists in business and commercial lending.
Business finance options to compare in 2026
- Business and franchise loans to buy, start or expand a business. Learn more.
- Equipment and vehicle finance to spread the cost of assets over their working life. Learn more.
- Commercial property loans for buying or refinancing premises. Learn more.
- Using equity in residential or commercial property, which can mean a lower rate than unsecured finance. Learn more.
Self-employed and need a home loan too? Our alt doc loans page explains how lenders can assess your income using BAS or business bank statements.
Every lender looks at businesses differently. Book a free loan review and we will compare bank and private lenders for you.
What lenders look at when you apply
Every lender has its own policy, but most business loan assessments come down to the same questions: can the business afford the repayments, how stable is it, and what happens if things go wrong?
- Trading history. Many lenders prefer two years of trading, although some will consider one year, or less with strong security.
- Financials. Tax returns, profit and loss statements, BAS and business bank statements show cash flow and serviceability.
- Security. Property, equipment or the asset being financed can lower the rate and lift the amount you can borrow.
- Director guarantees. Most lenders ask directors to personally guarantee the loan, even when the borrower is a company.
- Credit history. Both the business and the directors’ credit files are checked.
Secured or unsecured?
A secured loan uses an asset, often property or the equipment you are buying, as security. It usually comes with a lower rate, higher limits and longer terms. An unsecured loan is faster and does not put an asset on the line, but expect a higher rate, a shorter term and smaller limits. Many businesses use both: secured finance for big, long-term purchases and an unsecured facility or overdraft for short-term cash flow.
Questions to ask before you sign
- What is the total cost, including establishment, ongoing and exit fees?
- Is the rate fixed or variable, and can it change during the term?
- Can I make extra repayments or pay the loan out early without penalty?
- Are there conditions, such as regular financial reporting, I need to meet?
- Does the loan term match the working life of the asset I am financing?
Documents to have ready
Having these on hand can save days on an approval: two years of business and personal tax returns, recent BAS, year-to-date profit and loss, business bank statements, an asset and liability statement, and details of the asset or purchase. Because our team includes an accounting background, we can work alongside your accountant to present your numbers clearly.
Frequently asked questions
How long does business loan approval take?
It depends on the loan. Straightforward equipment or vehicle finance can be approved within days, while larger loans secured by property usually take a few weeks because of valuations and legal work. Having your documents ready speeds things up.
Can I get a business loan with less than two years trading?
Yes, some lenders will lend to newer businesses, especially with good security, industry experience or a strong deposit. Expect more questions and potentially a higher rate. We know which lenders are open to newer businesses.
Will a business loan affect my home loan?
It can. Personal guarantees and business debts are taken into account when you apply for a home loan, and using your home as security links the two. We look at your business and personal lending together so one does not limit the other.
Want advice for your situation?
Book a free, no-obligation loan review with MKS Lending Group. We compare 50+ lenders and explain your options in plain English.